You might be paying your bills on time, saving regularly, and contributing to retirement. But could you still be making financial mistakes without realizing it?
Not every financial mistake creates an immediate problem. Some go unnoticed for years, gradually reducing your savings or making important goals harder to reach. Carrying high-interest debt, missing employer 401(k) matching contributions, or overlooking changes in insurance needs can leave gaps in an otherwise reasonable financial plan.
Understanding where these problems arise can help you identify what needs attention. Here are seven common financial planning mistakes, their potential consequences, and practical ways to address them.
7 Financial Planning Mistakes and Why They Matter
Small financial decisions can have lasting consequences when common mistakes go unnoticed. The following seven areas highlight where problems can arise and what you can do to address them.
Not Having Enough Emergency Savings
Even with a steady income, an unexpected expense can strain your household budget if you don’t have enough savings to cover it.
A medical bill, major car repair, or sudden job loss may leave you relying on credit cards, borrowing from family, or using money intended for essential expenses. Without an emergency reserve, you could struggle to keep up with regular payments while managing the unexpected cost.
Building an emergency fund gradually, even through small contributions from each paycheck, can provide a financial cushion when circumstances change unexpectedly.
Carrying High-Interest Debt Without a Repayment Plan
Credit cards offer flexibility for everyday purchases, but carrying an unpaid balance can become expensive when interest charges accumulate.
Making only minimum payments may keep your account current, but it can also extend repayment for months or years, depending on your balance and interest rate. As a result, you may end up paying considerably more than the amount originally borrowed.
These ongoing charges can limit how much money you have available for other financial commitments.
A structured repayment approach, such as paying off the highest-interest balances first or tackling smaller debts for motivation, can help you manage interest costs and work toward becoming debt-free.
Missing Out on Employer Retirement Benefits
Some employers contribute additional money to their employees’ retirement savings. According to the Internal Revenue Service (IRS), workplace retirement plans, such as a 401(k), may include matching contributions based on how much an employee saves.
A 401(k) helps employees build retirement savings by contributing a portion of their earnings. Some employers also contribute additional funds based on how much an employee saves and the matching terms of their retirement plan.
For example, suppose you earn $60,000 annually and your employer matches your contributions dollar for dollar, up to 5% of your salary. If you contribute $3,000 during the year, your employer could contribute another $3,000, bringing your total retirement contribution to $6,000.
If you contribute less than the amount required for the full match, you could miss out on additional retirement savings and their potential growth over time.
Review your employer’s retirement plan to understand its matching requirements. If your budget allows, consider contributing enough to receive the full available match.
Not Updating Insurance Coverage After Major Life Changes
The insurance coverage that worked for you a few years ago may no longer fit your life today. Marriage, having children, buying a home, or changing jobs can introduce responsibilities that weren’t considered when you first purchased your policies.
For example, life insurance obtained before starting a family might not adequately account for a spouse, children, or mortgage obligations. Disability insurance also deserves attention because eligible policies can replace part of your income if a covered illness or injury prevents you from working.
Without suitable protection, your household could face financial difficulties during an already challenging situation.
Reviewing policy benefits, coverage limits, and exclusions after significant life events can help you identify areas that may require attention.
Letting Lifestyle Inflation Eat into Your Savings
A higher salary doesn’t always translate into greater financial progress. When spending rises alongside income, it’s easy to lose track of how much extra money is actually being saved. This pattern is known as lifestyle inflation.
For example, upgrading your car, choosing a more expensive apartment, or increasing spending on dining out and subscriptions may seem affordable after a raise. However, these additional costs can quickly consume the income increase.
Before committing to new expenses, consider allocating a portion of your raise to savings or other financial priorities. This allows room for lifestyle improvements without automatically spending every additional dollar.
Underestimating Retirement Expenses and Future Income Needs
Retirement may seem far away, but the amount you need to cover your living expenses could be higher than you expect. Planning around today’s costs without considering future changes can leave you financially unprepared.
As living costs rise over time, your money may not stretch as far as it does today. Everyday expenses, including groceries, household bills, and other necessities, could take up a larger share of your future budget. Healthcare can also become a significant expense, particularly when accounting for Medicare premiums, prescription medications, and potential long-term care needs.
Once regular paychecks stop, you may rely on Social Security, retirement accounts, and personal savings to cover these costs. If your income falls short, you might need to reduce spending or withdraw more from your savings than planned.
Estimating future expenses and comparing them with your expected retirement income can help you identify potential gaps before leaving the workforce.
Failing to Plan for Large, Irregular Expenses
Some expenses don’t appear in your monthly budget, but that doesn’t mean they’re unexpected. Property taxes, annual insurance premiums, school fees, and scheduled home maintenance are examples of costs you may know about months in advance.
When several payments fall within a short period, they can place pressure on your cash flow even if your regular monthly expenses are manageable.
One approach is to list these upcoming costs, estimate their annual totals, and divide those amounts into monthly savings targets. This can make larger payments easier to prepare for without disrupting your usual spending.
Which Financial Mistakes Should You Fix First?
When several financial concerns compete for your attention, deciding where to begin can be challenging. Consider the urgency and potential consequences of each issue before choosing your next step.
Ask yourself:
- What needs attention immediately? Identify overdue bills, essential living expenses, or obligations with approaching deadlines.
- What could cost more if delayed? Look for interest charges, penalties, or fees that may continue to increase.
- Where is your household most vulnerable? Consider whether an interruption in income or another unexpected event would affect your ability to meet basic needs.
- What can wait until later? Identify longer-term commitments that offer more flexibility without creating immediate financial difficulties.
Focus on the concern with the greatest potential impact, then address other issues as your situation allows.
How to Avoid Common Financial Planning Mistakes
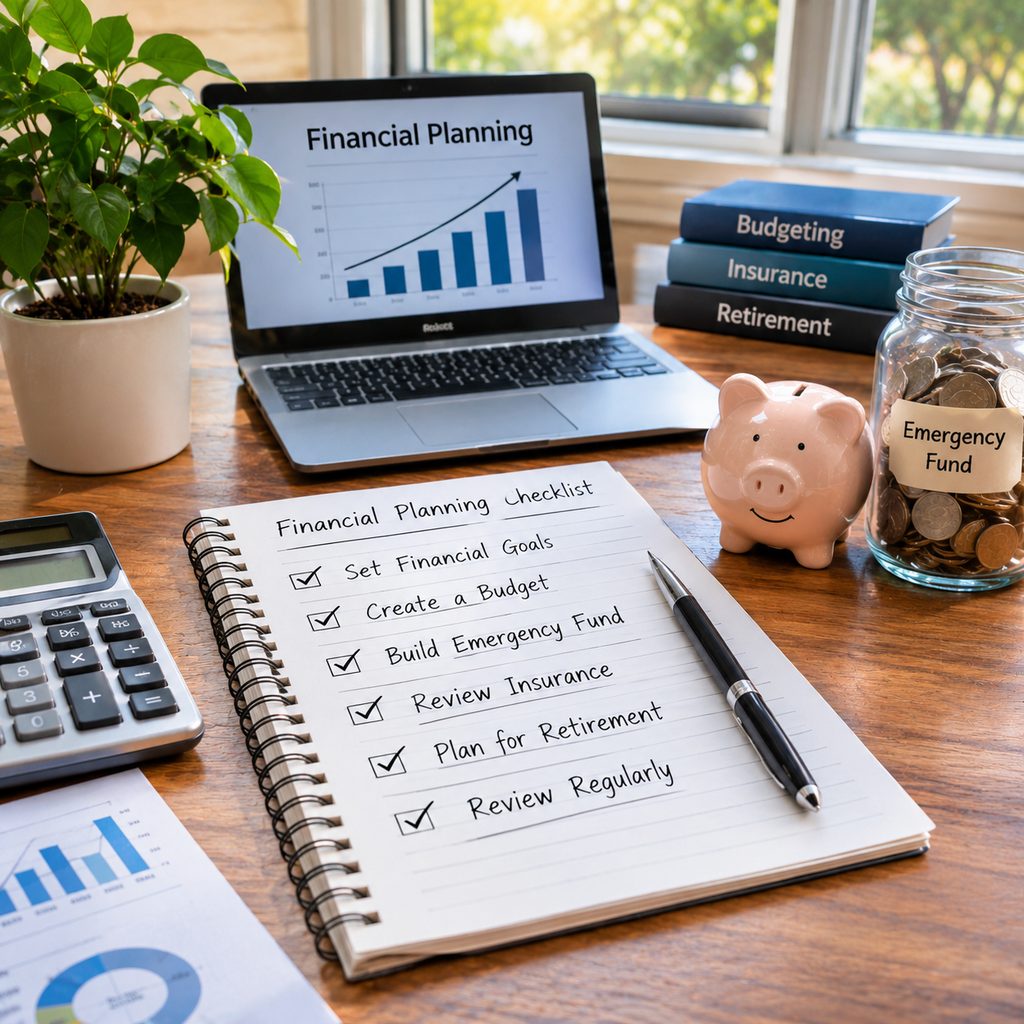
Once you’ve identified your main concerns, the next step is to develop habits that support better money management. The following strategies offer practical ways to strengthen your financial approach.
Set Clear and Realistic Financial Goals
Identify what matters most to you, whether it’s purchasing a home, paying for your child’s education, or preparing for retirement. Estimate the amount needed for each goal and establish an achievable timeline. Dividing larger targets into smaller milestones gives you a clearer path forward.
Create a Budget and Track Your Spending
Compare your monthly income with your regular expenses to see how your money is being used. Separate essential bills from optional purchases, and use a spreadsheet or budgeting app to monitor spending patterns. This makes it easier to spot unnecessary costs and decide where adjustments are possible.
Build an Emergency Fund and Prioritize Debt Repayment
Choose an affordable amount to save regularly while keeping up with required debt payments. After establishing a modest emergency reserve, consider putting additional funds toward high-interest balances. Adjust your approach based on your income and obligations so both priorities remain manageable.
Review Your Insurance Coverage and Retirement Savings
Check your life and disability insurance policies for coverage amounts, exclusions, and benefits that may need attention. Examine your retirement account balances and contribution rates in relation to your intended retirement date. Use these details to identify whether any adjustments are appropriate and affordable.
Review and Adjust Your Financial Plan Regularly
Schedule a financial check-in at least once a year or whenever your circumstances change significantly. Reassess your household commitments, upcoming expenses, and longer-term objectives to determine whether your overall approach still makes sense. This helps you respond to changes rather than relying on decisions made years earlier.
Frequently Asked Questions
1. What are the most common financial planning mistakes?
Common mistakes include insufficient emergency savings, high-interest debt, missed employer 401(k) matches, outdated insurance coverage, and underestimating retirement expenses.
2. How much should I have in an emergency fund?
A common guideline is three to six months of essential living expenses. Your ideal amount depends on your income stability, household needs, and financial obligations.
3. What financial mistakes should I avoid in my 30s and 40s?
Avoid excessive spending, neglecting retirement contributions, and overlooking changes in insurance needs. Balance current household responsibilities with preparations for future expenses.
4. How often should I review my financial plan?
An annual review is a practical starting point. Reassess your plan sooner if significant changes affect your income, family responsibilities, or financial circumstances.
Final Thoughts
Financial planning isn’t about making every decision perfectly. It’s about recognizing potential risks and choosing an approach that works for your situation. Paying attention to everyday financial habits can help you prepare for both immediate responsibilities and future needs.
For those seeking additional guidance, KABCO Group offers financial coaching and insurance solutions to help individuals and families understand their options and navigate important financial decisions.